

Possible: Fast Cash & Credit
by Possible Finance - A Public Benefit Corporation
4.4
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.4
- Price
- Free
- Download
- 1.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
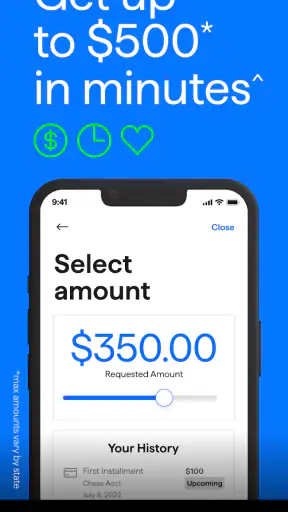
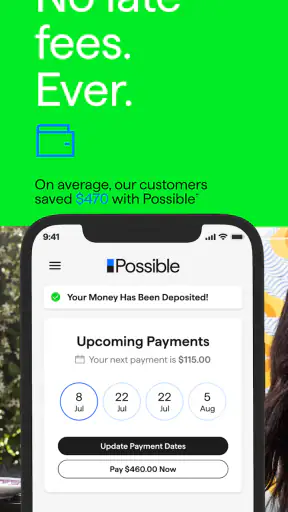
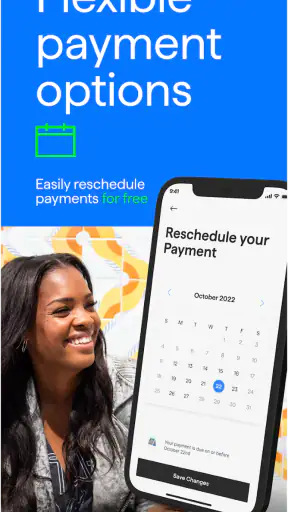
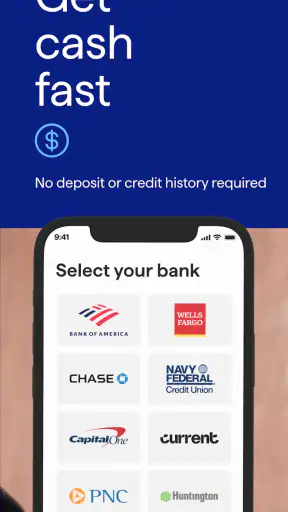
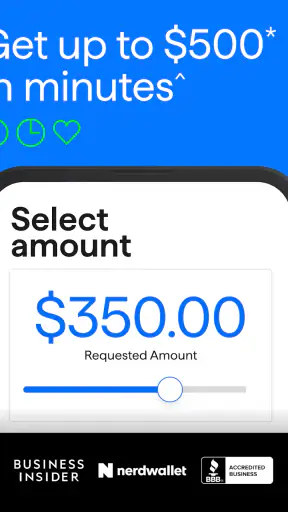
 Analysis by Getfullapps
When an unexpected bill lands between paydays, the hardest part is often not finding an app but understanding what will happen after you tap “apply.” Possible: Fast Cash & Credit is a finance app from Possible Finance - A Public Benefit Corporation that is built around short-term access to cash and the chance to build credit. I found its appeal easy to understand: it tries to make a stressful money problem feel more manageable by putting the application and repayment process in one mobile experience.
My overall impression is positive, but I would not treat it as free money or as a replacement for a proper emergency fund. The app is free to install, has an Everyone age rating, and has become a widely used option with more than a million installs. Its average rating is 4.4 from roughly sixty-three thousand ratings, which suggests that many people find the experience useful, while still leaving room for the reality that borrowing apps can feel very different depending on a person’s situation.
What to expect before you apply
The first thing I would tell a new user is to separate the app itself from the financial product it may offer. Downloading Possible costs nothing, but using a cash advance or credit-building service involves financial commitments that deserve careful attention. The store summary focuses on getting cash quickly, building credit, and using flexible payments. Those are meaningful goals, but each one depends on your eligibility, the terms shown during the application, and your ability to repay on schedule.
That distinction matters because the app is not simply a budgeting tool. A budgeting app helps you organize money you already have; Possible is aimed at people who need access to money and want a structured way to handle repayment. If your problem is that you cannot see where your monthly spending goes, a budget tracker or bank account with built-in planning tools may be a better first step. If the problem is a specific shortfall before your next income arrives, this app is more directly relevant.
I also appreciate that the service is presented as a credit-oriented option rather than only a quick-cash button. Building credit can be valuable when you are trying to qualify for more affordable financial products later. Still, I would avoid assuming that one successful repayment instantly transforms a credit profile. Credit outcomes depend on reporting, account history, and other parts of your financial record. The sensible approach is to view Possible as one tool in a longer plan, not as a shortcut around every credit problem.
The app was released on January 25, 2018, and the current version is 2.5.0. It requires iOS or Android version 10 or later, so compatibility is worth checking before you spend time on setup. The developer is Possible Finance - A Public Benefit Corporation, a detail that may reassure users who prefer to know who operates a finance service, although it should not replace reading the actual terms presented inside the app.
The right mindset for a first-time user
I recommend opening Possible when you can give the application your full attention, rather than while rushing through a checkout line or dealing with a collection of urgent notifications. Have a clear reason for the money in mind. “I need to cover a necessary bill until my next income” is a more useful starting point than “I want extra spending room.” That simple distinction helps you judge whether repayment will fit your next pay cycle.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
A realistic example would be a household facing a utility bill a few days before payday. The user could review the available offer, compare the repayment dates with the expected income date, and decide whether the arrangement solves the timing problem without creating a larger one. The important step is not merely receiving the money; it is checking that the repayment schedule leaves enough for rent, food, transport, and other fixed obligations.
For someone already juggling several loans, overdrafts, or late payments, I would be cautious. Adding another repayment can make the calendar harder to manage even if the individual amount looks small. In that situation, speaking with a nonprofit credit counselor or contacting existing creditors may be more appropriate than opening another borrowing channel.
Setting up the account without unnecessary confusion
The setup experience is easier to approach if you treat it like a financial application rather than a casual app registration. Read each screen before continuing, especially when the app asks for information needed to assess eligibility or connect the service to your financial situation. Entering details accurately is not just an administrative chore; mismatched information can slow down the process or make the result harder to understand.
I would keep your identification and banking details close at hand, use an email address and phone number you regularly monitor, and avoid beginning the process on a device you do not control. Finance apps are not the place for a rushed setup on a shared phone. Once the account is created, use the security options available on your device and keep the app updated. The current version is 2.5.0, and staying current is a sensible habit for any app that handles sensitive financial activity.
One useful preparation step is to review your upcoming calendar before applying. Mark your next income date, rent or mortgage date, subscription renewals, and any existing automatic payments. This gives you a practical test for any offer shown in Possible. Rather than asking only, “Can I receive this amount?” ask, “What will my account look like on every repayment date?” That second question is where many borrowing decisions succeed or fail.
The app is free, but that should not be confused with the total cost of using a financial product through it. Look closely at the amount you receive, the total amount to be repaid, the dates involved, and any other terms displayed before accepting anything. If a screen is unclear, pause and reread it. A fast decision is not necessarily a good decision, particularly when the consequence appears later in your bank balance.
How to evaluate the first offer
Possible is most useful when you compare the offer with your actual cash-flow plan. I would write down three figures before accepting: the money that will arrive, the total repayment obligation, and the amount you expect to have left after essential expenses. Keeping those figures separate prevents the common mistake of treating the approved amount as disposable income.
There is also a psychological advantage to deciding your repayment plan before taking the money. If the cash is intended for a car repair, medical expense, or utility bill, keep it reserved for that purpose. Moving it into everyday spending makes it difficult to tell whether the app solved the original problem. A separate mental envelope, or a separate place in your personal budget, can make the repayment feel less surprising when it appears.
Users interested in credit building should be especially disciplined. The potential benefit comes from responsible repayment behavior, not from repeatedly borrowing simply to create activity. If you can repay comfortably, the service may fit a broader effort to establish a stronger financial history. If repayment would require another advance, the credit-building goal is being undermined by the borrowing cycle.
Reaching the first meaningful success
For a first-time user, success is not just getting approved. I would define the first meaningful success as completing one carefully planned borrowing experience without missing a payment or disrupting essential bills. That starts with using the app to understand your available option, accepting only what matches the need, and recording the repayment dates somewhere you already check regularly.
After the money arrives, resist the temptation to stop looking at the app until the due date. Check the repayment schedule and make sure your bank balance plan still makes sense after other transactions clear. A small change in income or an unexpected purchase can turn a comfortable plan into a tight one. Early awareness gives you more choices than discovering the problem on the day a payment is due.
I would also take a moment after repayment to review what actually happened. Did the money arrive in time for the bill? Did the repayment dates match your income? Did the service reduce stress, or did it make the following weeks more difficult? These questions are more valuable than judging the app only by speed. If the experience worked, you will know the specific situation in which it helped. If it did not, you have a clear reason to look for a different solution next time.
A practical workflow looks like this:
Identify the essential expense and the exact timing problem.
Review the offer and terms inside Possible before accepting.
Compare each repayment date with income and existing automatic payments.
Reserve the money for its intended purpose.
Monitor your balance and repayment progress instead of relying on memory.
This workflow may sound cautious, but it is what makes a cash-access app useful rather than risky. The application can simplify the process; it cannot decide whether the repayment fits your life. That judgment remains yours.
Where the credit-building promise fits
Possible stands apart from an ordinary cash advance app because credit building is part of its identity. That makes it interesting for someone who has limited credit history and wants financial activity to support a longer-term goal. However, I would not choose it solely because the phrase “build credit” sounds attractive. Confirm how the product works for your account, understand what behavior is expected, and keep your expectations realistic.
For people with established credit, a conventional credit card or personal loan may offer a more familiar structure and potentially a better fit, depending on the terms they can qualify for. A bank overdraft may be simpler for a very small, very brief gap, while a local credit union could be worth comparing for a larger planned expense. Possible is strongest when accessibility and a mobile-first process matter, especially for someone who needs a clear short-term arrangement and is focused on responsible repayment.
The trade-off is that convenience can encourage impulsive use. A traditional application often forces you to slow down and compare alternatives; a phone makes borrowing feel close to ordinary shopping. I think Possible deserves a deliberate pause before acceptance for exactly that reason. The easier the process feels, the more important it is to examine the obligation behind the interface.
Common points of confusion during everyday use
One common misunderstanding is assuming that approval is guaranteed because the app is designed to provide fast access to cash. It is better to treat every application as an assessment with an outcome that depends on your circumstances. Start the process with an alternative plan in mind, particularly if the bill is urgent. That might mean asking the provider for a short extension, checking an employer advance policy, or contacting a trusted support organization.
Another source of confusion is the difference between receiving money and being financially better off. The deposit can solve a timing issue, but the repayment still has to leave your account later. I find it helpful to imagine the repayment as already spent. If your next pay cycle cannot absorb it while covering essentials, the app is probably not solving the problem in a sustainable way.
Users can also overlook the importance of payment timing. A schedule that looks comfortable on paper may collide with rent, a subscription, or a bill that is charged automatically. Put every date into one calendar, including the Possible payments, and review the week rather than only the individual day. This is a small but non-obvious habit that can prevent several financial commitments from landing together.
Credit-building language can create a second misunderstanding: the idea that any borrowing is beneficial. Responsible, affordable repayment is the meaningful behavior. Repeatedly taking advances, borrowing more than necessary, or using one advance to cover another can increase pressure instead of improving your position. If the app becomes part of a repeating cycle, that is a signal to stop and seek a broader solution.
Finally, remember that a high user rating does not mean the product will suit every borrower. Possible has an average rating of 4.4, and its roughly twenty-nine thousand written reviews indicate substantial user discussion, but personal eligibility, income timing, existing obligations, and repayment capacity matter more than a general score. Reviews can tell you how people experience the interface; they cannot decide whether a particular offer is affordable for you.
When I would choose another option
I would skip Possible if I needed money for a nonessential purchase and had no clear repayment plan. I would also hesitate if my income were unpredictable, if several payments were already late, or if accepting the offer would leave no buffer for food and housing. In those cases, the app’s speed is less important than reducing the underlying financial pressure.
For a planned expense that can wait, saving gradually is usually healthier. For an existing debt problem, a counselor or creditor negotiation may address the cause more directly. For a person with strong credit and time to compare rates, a conventional financial product could be more suitable. Possible is not automatically the cheapest or best answer simply because it is convenient.
The next step after the first repayment
Once you have completed the first cycle, decide whether the service belongs in your financial toolkit at all. If it helped with a genuine short-term timing issue and the repayment felt comfortable, keep the app available but do not create a reason to use it. The best outcome is that it remains an emergency option rather than becoming a regular line in your monthly budget.
If credit building is your main goal, pair the app with habits that do not require borrowing: paying every account on time, keeping track of balances, reviewing your credit information where available, and building even a small emergency reserve. Possible can be one part of that plan, but it cannot replace the wider routine. The more alternatives you create, the less pressure there is to accept an offer on an inconvenient day.
I would also review the app after a few weeks of normal use for practical reasons. Is the repayment information easy for you to find? Are notifications reaching you? Do the dates fit the way you are paid? Are you using the app for planned needs or for routine spending? These answers tell you more about whether it works than the initial download experience does.
The app’s Everyone rating makes it broadly approachable from an age-classification perspective, but financial responsibility is still personal. A young adult, a worker with irregular income, and someone rebuilding credit may all open the same app while needing very different guidance. The safest user is the one who reads the terms, understands the schedule, and has a backup plan before accepting money.
After spending time with Possible, I see it as a focused finance app for people who value a mobile application process, need a short-term cash solution, and are willing to manage repayment carefully. Its free installation, long availability since 2018, and large user base make it easy to consider, while the credit-building angle gives it more purpose than a simple emergency-cash tool. The limitations are just as important: convenience can encourage overuse, the offer must be judged on its own terms, and no app can make an unaffordable repayment safe.
My recommendation is to install Possible only when you can name the expense, map the repayment dates, and explain how the arrangement supports your wider financial plan. Used that way, it can be a practical bridge during a temporary gap. Used without that preparation, it may postpone the problem rather than solve it. For a first-time user, the most reassuring path is also the most disciplined one: set up carefully, read before accepting, reserve the money for its purpose, and treat a successful repayment—not a fast approval—as the real measure of value.
Pros
- Quick application process with minimal paperwork
- Clear repayment terms shown before accepting an offer
- Useful for handling unexpected short-term expenses
- Account management is convenient from a mobile device
- May help users compare available borrowing options
Cons
- Approval and loan availability may vary by location and eligibility
- Interest rates and fees can make borrowing expensive
- Late payments may lead to additional charges or credit damage
- Not suitable as a long-term solution for recurring expenses
- Some features may require sharing sensitive financial information
FAQs for Possible: Fast Cash & Credit
What is Possible: Fast Cash & Credit, and how does it work?
Possible: Fast Cash & Credit is a financial app designed to let eligible users apply for short-term credit through a mobile device. After creating an account, you provide personal and financial information, choose an available borrowing option, and review the repayment terms before accepting. Approval, loan amounts, fees, and availability depend on factors such as your application details, state regulations, and the lender’s assessment.
Who can apply for credit through Possible?
Eligibility requirements can vary depending on where you live and the product offered at the time of application. In general, applicants may need to be adults with a valid government-issued identification document, an active bank account, a reliable source of income, and a compatible mobile phone. Downloading the app does not guarantee approval, so carefully review the current requirements before submitting sensitive information.
How much does Possible cost, and are there fees?
The total cost depends on the credit product, your location, and the terms displayed in the application. Possible may disclose finance charges, subscription costs, late fees, or other applicable charges before you accept an offer. Because short-term credit can be expensive compared with traditional borrowing, read the agreement carefully, check the annual percentage rate or equivalent cost, and confirm the repayment schedule.
How are repayments made in the Possible app?
Repayments are generally scheduled through the bank account or payment method connected to your Possible account, according to the agreement you accepted. The app may show upcoming due dates, payment amounts, and account activity, which can make it easier to monitor your balance. Make sure sufficient funds are available, since failed or late payments could lead to additional charges or other financial consequences.
Is Possible: Fast Cash & Credit safe to use?
Possible uses account and identity information to evaluate applications and manage credit, so users should review its privacy policy, permissions, and security practices before signing up. Only install the official version from a trusted app store, use a strong password, and avoid sharing login codes. Most importantly, compare the complete cost with alternatives and borrow only an amount you can repay on time.

Possible: Fast Cash & Credit
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via help@possiblefinance.com, visit http://www.possiblefinance.com, or review their https://www.possiblefinance.com/privacy-policy/.










